
GSTAT: Interest on Delayed Refund runs from Original Application despite Refund being Sanctioned within 60 Days
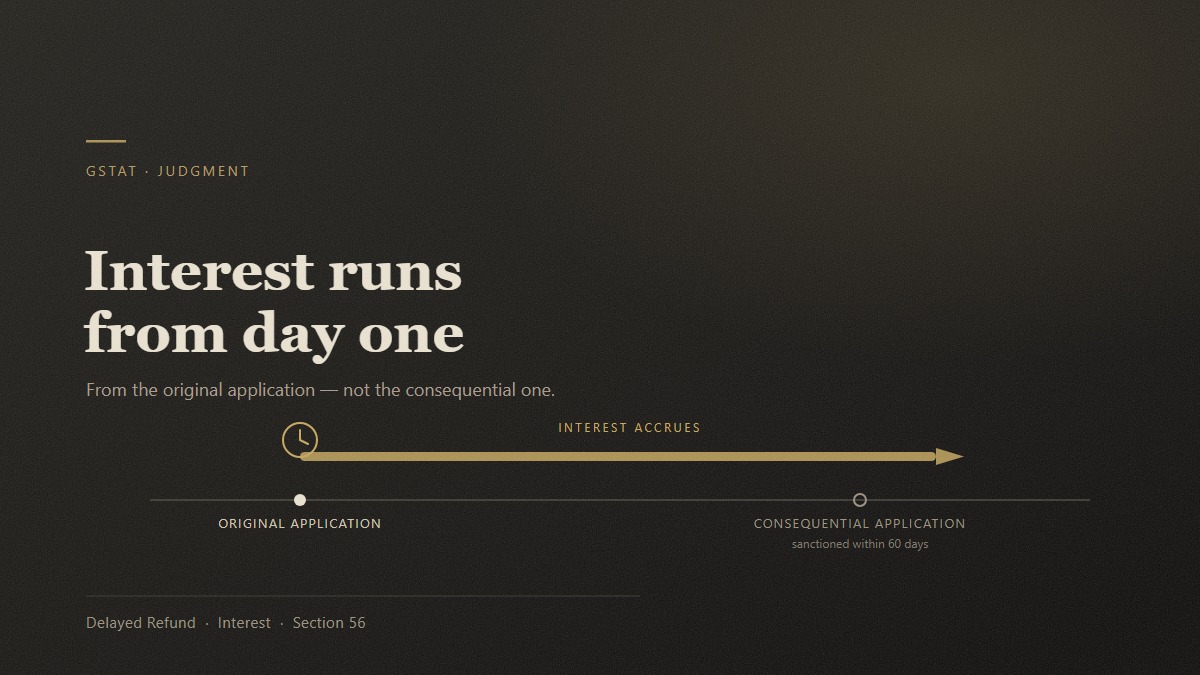
GSTAT Vijayawada holds that a taxpayer whose refund claim is initially rejected but subsequently allowed in appeal remains entitled to interest u/s 56 of the CGST/APGST Acts at 6% from the expiry of 60 days from the original refund application. The Tribunal clarifies that a consequential refund application filed after a favourable appellate order facilitates implementation and disbursement of the refund, thus it does not reset the starting point for calculating ordinary interest or extinguish interest accrued on the original claim. GSTAT further holds that the proviso to Section 56, providing for enhanced interest at 9% where the consequential refund is not granted within 60 days, operates separately and does not replace or dilute the entitlement under the main provision. Relying on a series of judgments by Apex Court such as Ranbaxy Laboratories, Qualcomm India, SBI Cards, etc, the Tribunal rejects the Department's contention that payment within 60 days of the consequential applications defeats the earlier interest claim. Accordingly, GSTAT sets aside the orders denying interest and directs the proper officer to calculate interest separately for the eight refund claims, from the expiry of 60 days after each original application until actual disbursement, subject to verification, and disburse the amount found payable within eight weeks.